India is getting fitter.
Is your portfolio?
A premium 24/7 Anytime Fitness club in one of Chennai’s established residential and commercial catchments — a data-led ₹3.50 Cr project with recurring membership revenue, a confirmed fixed-royalty franchise structure, and a catchment built for it.
All figures are indicative and illustrative. Illustrative financial model. Member ramp, revenue and cost assumptions are planning assumptions, not Anytime Fitness guarantees. Investors will receive the official P&L from AF.
USD figures converted at a fixed ₹100/US$ — switch anytime with the ₹/$ toggle.
Why this opportunity merits your time
Five reasons — each examined in detail as you keep scrolling.
Growing fitness market
Chennai counts among India's top-ten tier-1 fitness hubs, and organised fitness is scaling fast across urban India.
Established franchise model
Anytime Fitness brings a globally proven club operating framework — brand, systems, technology and support.
Strategic location
Adyar combines residential density, commercial activity, education and affluent households in one catchment.
Recurring membership model
Annual memberships create a recurring, subscription-led revenue base rather than transactional income.
Multiple revenue streams
Membership plus personal training plus ancillary revenue diversify income and lift margins with scale.
Fixed costs. Growing memberships. Expanding margins.
Why Anytime Fitness
A globally established 24/7 fitness franchise with a proven club operating model — evidence, not promotion.
Brand, systems, technology and support — a proven operating framework.
Global footprint
24/7 modelSource: Per Anytime Fitness franchise materials. Figures to be reconfirmed in the final franchise agreement.
The model, in one line
- 24/7 access and global club reciprocity create a differentiated member proposition.
- AF India markets a fixed monthly royalty rather than a percentage-of-sales royalty — operating leverage as the club scales.
- Limited South India presence today; one established club in Anna Nagar, Chennai (2014).
- Significant franchisee autonomy across the project, including end-to-end control of fit-out and execution.
Fixed royalty, growing leverage
Confirmed · ₹1.7 L/moAs monthly revenue scales, the fixed ₹1.7 L/month royalty falls from 17% to 5.7% of revenue — the operating-leverage engine of the model.
Commercial terms
Project investment per the ₹3.50 Cr use-of-funds plan — see section 08.
The fight for Chennai's fitness rupee
Cult.fit's IPO-scale expansion proves organised-fitness demand in urban India. The question for Adyar: which model wins the neighbourhood?
Cult Adyar (4.8★) is not a threat to fear — it is proof of demand. The premium 24/7 position in this catchment is open, and the deck’s plan is to compete on brand, hours, service, PT and member experience rather than price.
The demand story behind it
Cult.fit revenueSources: Cult.fit IPO materials and public reporting, 2026; business.cult.fit franchise disclosures. Temasek raised its stake with a ₹440 Cr investment (2026).
The wider competitive set
Local listings indicate a dense competitive set around Adyar. Multiple established gyms demonstrate proven fitness demand in the micro-market.
- Cult Adyar · LB Road4.8★ · group-fitness ledValidates premium demand inside the catchment
- Gold's Gym · Shastri Nagar4.3★ · mainstreamLeads the conventional segment
- Anytime Fitness · Anna NagarEst. 2014AF's only Chennai club today — the brand has room to grow
Ratings from public Google Maps listings, 2026. Full three-way operator table in the investor deck.
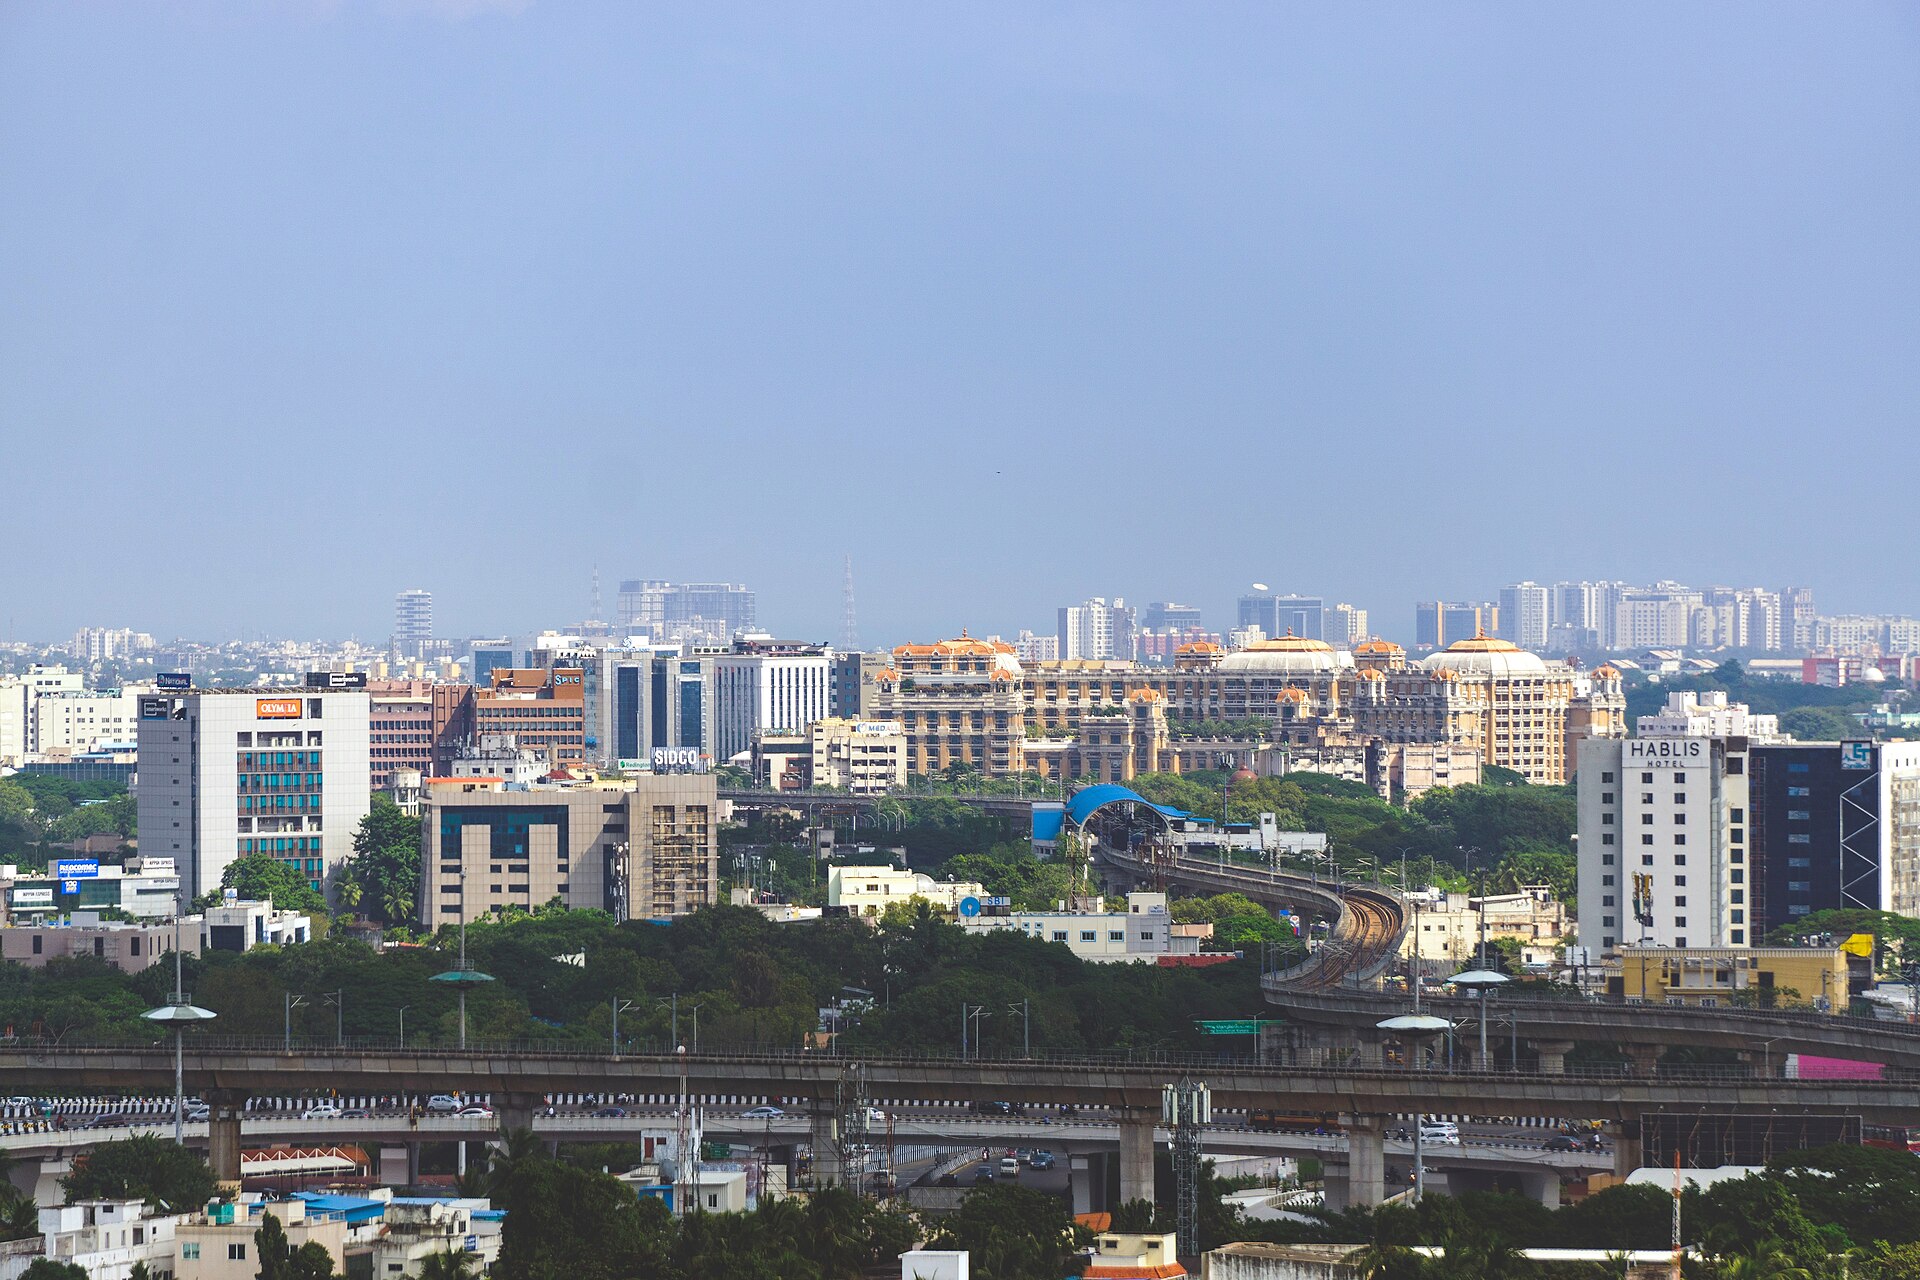
Why Adyar
Established residential density, premium households and strong daily movement — with proven demand from the gyms already operating in the micro-market.
Catchment dashboard
1.5 km radiusSource: GapMaps Catchment Report, June 2026 (1.5 km radius). India Census 2011; GapMaps 2024.
Addressable market
Adjustable assumptionsRequires modest pull from the secondary catchment (69,409 workers within the catchment, plus Besant Nagar to Thiruvanmiyur) to reach the Year-5 target.
Why this can become more than a single gym
Prove · Replicate · ScaleAdyar proves the model. Once the operating playbook, sales engine and local brand presence are established, the same format extends into Chennai’s other established premium residential markets at lower execution risk.
Sholinganallur potentially two clubs across the OMR corridor.
The proposed club
Core objective: reach a stable membership base while increasing PT penetration and maintaining disciplined rent and staffing costs.
Membership
Accessible premium pricing with monthly and annual options.
Personal Training
High-margin secondary revenue stream, modelled at 22% of membership revenue.
24/7 Access
Convenience for professionals and local residents — a key differentiator in the catchment.
Technology
Member management, access control and engagement through the AF App.
Community
Retention through challenges, events and coaching.
Operational Excellence
Lean staffing and strong sales discipline.
Equipment & fit-out
- Cardio: 4 treadmills, cross-trainers, upright / recumbent / spin bikes
- 11 strength stations, racks and benches
- 800–1,000 kg free weights
- Evolt body-composition analysis and AED
- Access control with 500 key fobs, CCTV
Gym manager, fitness manager, 4 trainers + 2 assistants, 7 freelance PTs, 3 sales, housekeeping, security.
Path to opening
- Day 0Franchise fee paid
- Day 30Lease registered, deposit paid
- Day 35Equipment advances placed
- Day 40Fit-out kick-off & pre-sales launch
- Day 90Club opening
Club walkthrough video and 3D site visualisation will be embedded here as the project advances.
A five-year model you can interrogate
The base case reflects the promoter's current operating assumptions. Change any assumption and every table, chart and ratio on this page recomputes instantly.
Assumption calculator
Illustrative 5-year P&L
Base case before depreciation, interest and tax
| Y1 | Y2 | Y3 | Y4 | Y5 | |
|---|---|---|---|---|---|
| Members (avg) | 650 | 900 | 1,050 | 1,150 | 1,200 |
| Revenue | ₹2.07 Cr | ₹2.87 Cr | ₹3.35 Cr | ₹3.67 Cr | ₹3.83 Cr |
| Operating costs | ₹1.61 Cr | ₹1.90 Cr | ₹2.08 Cr | ₹2.20 Cr | ₹2.26 Cr |
| EBITDA | ₹46.71 L | ₹96.99 L | ₹1.27 Cr | ₹1.47 Cr | ₹1.57 Cr |
| EBITDA margin | 23% | 34% | 38% | 40% | 41% |
Illustrative financial model. Member ramp, revenue and cost assumptions are planning assumptions, not Anytime Fitness guarantees. Investors will receive the official P&L from AF.
Break-even
Monthly members required to cover all operating costs — test a rent move and watch it respond.
Sensitivity — Year 5
Downside thinking, not just the base case. Highlighted row = current scenario.
| Y5 members | Revenue | EBITDA | Margin |
|---|---|---|---|
| 900 | ₹2.87 Cr | ₹96.99 L | 34% |
| 1,000 | ₹3.19 Cr | ₹1.17 Cr | 37% |
| 1,100 | ₹3.51 Cr | ₹1.37 Cr | 39% |
| 1,200 | ₹3.83 Cr | ₹1.57 Cr | 41% |
| 1,300 | ₹4.15 Cr | ₹1.77 Cr | 43% |
| 1,400 | ₹4.47 Cr | ₹1.98 Cr | 44% |
| Monthly yield | Revenue | EBITDA | Margin |
|---|---|---|---|
| ₹1,600 | ₹3.06 Cr | ₹1.09 Cr | 36% |
| ₹1,700 | ₹3.26 Cr | ₹1.21 Cr | 37% |
| ₹1,800 | ₹3.45 Cr | ₹1.33 Cr | 39% |
| ₹1,900 | ₹3.64 Cr | ₹1.45 Cr | 40% |
| ₹2,000 | ₹3.83 Cr | ₹1.57 Cr | 41% |
Where the money goes — and what it could return
₹3.50 Cr project, funded by investors and the promoter together. Investors receive 90% of the equity pool pro-rata to cash; the promoter operates the club for 10% sweat equity, a 20% management fee on revenue, and pro-rata equity on any balance capital.
Use of funds
₹3.50 Cr- Franchise fee incl. taxConfirmed₹30 L
- Fit-out / interiorsAssumption₹1.00 Cr
- Gym equipmentAssumption₹1.20 Cr
- HVAC / electrical / other MEPAssumption₹20 L
- Lease deposit / pre-openingAssumption₹50 L
- Working capital / launch marketingAssumption₹30 L
Investor vs promoter equity
Illustrative funding structure. Investors fund the full project cost for 90% of the equity; the promoter operates the club for 10% equity plus a 20% management fee on revenue (over and above the ₹1.70 L/month AF royalty). Final terms subject to definitive agreements.
Illustrative investor returns
Not an offerInvestors fund 100% of the ₹3.50 Cr project; the 90% cash-equity pool is allocated pro-rata among investors. Modelled on the base-case P&L — after the promoter’s 20% management fee and the AF royalty.
Illustrative investor return scenarios — not an offer or a guarantee. Ownership, preferred return, distribution policy and exit mechanism are subject to definitive agreements.
Capital raise is planned across multiple investors; the investor equity pool is allocated pro-rata to capital contributed.
Risks & mitigation
Stated plainly, because a model without downside thinking is just a brochure.
| Risk | Potential impact | Mitigation |
|---|---|---|
| High rent / poor lease | Margin compression | Cap rent; negotiate rent-free fit-out period; site approval before signing |
| Member acquisition slower than plan | Delayed break-even | Pre-sale targets; local marketing; corporate partnerships |
| Competitive density | Pricing pressure | Differentiate on AF brand, 24/7, service, PT and member experience |
| PT underperformance | Lower secondary revenue | Trainer hiring, targets, PT packages and conversion tracking |
| Franchise agreement terms | Long-term economics | Legal review; confirm territory, renewal, transfer and fee schedule |
Data room
Core documents behind this page — click any document for an in-page preview, download it, or open it in a new page. Additional materials are shared directly during investor discussions.
Provided with this page
Shared on request
- Franchise agreement & fee scheduleon request
- Site information & lease proposalon request
- Floor plan & fit-out specificationon request
- Capex quotations (equipment, fit-out, MEP)on request
- Proposed company structure & shareholder termson request
Request via WhatsApp (+61 410 209 290) using the investor enquiry button below.
Ready to talk
numbers?
5,000 sq ft · Adyar, Chennai · ₹3.50 Cr project, 100% investor-funded
WhatsApp +61 410 209 290